M05 - Formation of insurance contracts & Insurable Interest
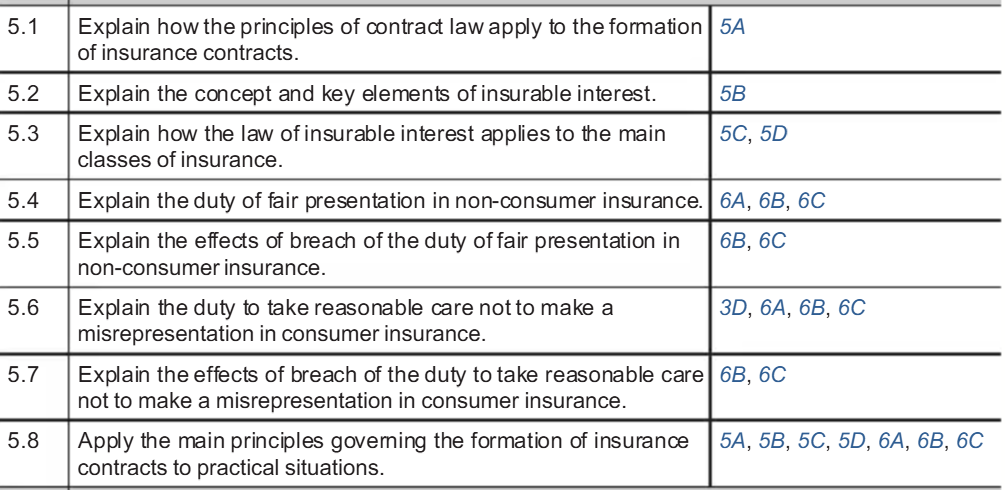
- How does law support insurance contract formation
- Insurable interest what and why
- Insurable interest applies to Classes
- Duty of fair presentation in non consumer insurance and effects of breach in duty.
- Duty to take reasonable care not to make a misrepresentation in consumer insurance and effects of breach in duty
- Main principles governing formation of insurance contracts to practical situations
5.1 Principles of contract law apply to formation of insurance contracts
Offer and acceptance in insurance - once the offer made by 1 party is unconditionally accepted by the other
Invitations to treat - True offers and invitations to treat (enter into negotiations)
Who makes the offer
Different options
- Proposal form - Submitted to insurer and this may quote a premium based on the information supplied in PROPOSAL FORM in doing so make an offer which may be accepted or declined
- lengthy negociations results in back and forth
Law of contract - in principle an offer cannot be accepted by doing nothing and that acceptance must generally be communicated to other party
If renewal notice received then cover given if not then no. A fresh contract is formed
- Fresh offer and acceptance are therefore required
- If the risk has changed in any material way. The insureds must be notified allowing insured to a counter offer which the insurers may or may not accept
What must be agreed? An acceptance will be effective only if the parties agree on the essential terms of the contract
- Nature of the risk + subject matter of insurance
- Duration of the contract
- Amount of premium
meeting of minds
Signing down is a contract change in premium per insurer BUT the MRC includes a Provision!!!
Risk begin to run
Binding contract to insure but risk has not yet attached.
Contractual intention and insurance
No legally binding contract will be formed unless the parties intended to be legally bound.
Contractual intention - presumed to exist unless strong evidence to the country
English law a promise is not legally binding unless supported by consideration ie unless something of value is given in exchange for it!!!
Premium payable and given the insurer is the promise to pay claims.
Unless parties have agreed otherwise, the risk attaches although premium has not been paid.
- Insurers can agree in advance to extend the policy to cover some risks excluded from original contract if needed. with additional premium
Return of premium under insurance contracts
When on risk, the insured is not entitled to any return of premium if the contract is subsequently ended prematurely. However if not on risk then recovery is possible "Total failure of consideration" EG
- proposal withdrawn after premium has been premium paid
- policy may be void for mistake, no insurable interest, ad inito
pre contract rules and remedy to breach to duty are different for consumer and business. Life insurance policies where no insurable interest
Illegality in insurance contracts
Cancellation clauses
Terms of a contract can modify rules.
- Insurers often include a clause allowing them to cancel the policy mid-term with a given notice period to the insured. PRO RATA premium
- Insured may also be given the right to cancel the policy although something less than. (Eg property is sold)
Formal requirements of insurance contracts
Insurance cover may be given orally and written policy issued. Exceptional cases required by law
- Contracts by deed
- Insurance contracts which must be in writing - Marine policy specify name of the insured or their agents or behalf of the insurer. specify subject matter of insurance with reasonable certainty
- Insurance contracts must be evidenced in writing
- written documentation is required ie CAR insurance or Life insurance
Policy shall contain the name of person interested in it and rights to cooling off period
Capacity to contract
Minors and disability/drunken persons
Contractual capacity of insurers
Main statues covering insurance companies are now financial services and market act 2000 and financial services act 2012.
Lloyds is self regulated
Unlicensed insurers
Financial service act 1986 - allowed insurance companies to to choose wether to enforce the contract. (replaced by insurance companies act 1982). What is the current landscape of Acts
Recall "EEA passport rights"
5.2 Concept and key elements of insurable interest
Means policyholder must be in a position where they will suffer loss if the event which they have insured against occurs.
- Subject matter of insurance
- policyholder must have economic / financial interest in insurance matter
- Current interest
- legal interest
"Subject matter" - What interest does entity have in property (House, solar, wind) eg destruction or loss. Human life
Value of life is unlimited. However for a creditor in the life of a debtor. easier to measure.
Current interest is not merely an "expectancy"
Napoleonic war - crown commissioners insured ships once at port the law on insurable interest
Legal interest
The interest must also be a legal interest
EG Timber held by a legal entity (Company). Will shareholder has a legal interest? NO!
recently a pub owned by a company went into liquidation due to financial difficulties. Agreed to sell pub to B and buy insurance. Pub was destroyed priot to completion of sell. B insurers asserted B has no insurable interest therefore did not have to meet the claim.
BUT
B and liquidators had entered into binding agreement which granted a licence to use the property pending purchase on the condition B obtained insurance.
Why law requires insurable interest
Reduce moral Hazard
Discourage wagering
- Insurable interest vs a wager. Where do they differ
Financial interest in subject matter of the contract
Object is to protected the insured against loss and their identity before the event
pre contractual information duty
Payment is only made by indemnity
Contract is enforceable at law
Creation of insurable interest
Common law - Assumed to exist, (every person has unlimited interest in their own life).
Ownership - Car carries with right to insure
Contract - accept responsibility for something for which they would not ordinarily be liable
EG Lease for a house contains condition which makes the tenant responsible for maintenance or repair of the building (GIVING tenant financial interest in the property which is insurable) lease may also make tenant liable to pay rent even if building is uninhabitable further supports their interest.
EG Liability of Reinsurers to make payments to insurers arises out of agreement contain in contract.
5.3 Explain the law of insurable interest applies to main classes of insurance
Law of insurable interest
Marine insurance
Marine insurance act 1907 provides that the insured must be interest in subject matter insured at time of loss.
section 6 allows insured to claim on subject matter even if they acquire their interest after the loss occurred. Unless they were aware of the loss and the insurer was not.
- cargo changes owner ship during transit
- Marine insurance policy is assigned to the new owner along with other documents (Transfer of title)
- Buyer is protecte dby policy even though they acquired their interest in the goods some time after the policy date.
Life and other classes of insurance
Life assurance act 1774 - Condemns "Mischievous form of gaming" shall have no interest or by way of gaming or wagering
Provisions in the ACT
- Benefiting from the insurance must have an insurable interest in th life or event insured. or contract is void
- Name of the person for whose benefit the policy has been effected must appear in the policy
- Insured can recover no more than amount of the value of their interest
- Act does not pply to insurances on ships, goods ore mechandies
Does this act apply to property see Other insurances
Time when interest is required
life insurance, insurable interest is require at time when contract is made
the insurable-interest rule prevents wagering when the policy is created; once that requirement is met, a later disappearance of the interest does not invalidate a life policy. (Dalys vs Duke of cambridge)
Policies on goods are not subject to any statutory requirements of insurable interest other then goods involved in marine adventure.
Legislation on gambling
Effect of the principle of indemnity
Effect of a policy without interest
Effects of illegality pari delicto - void contract is usually recoverable
Harse vs pearl life insurance - Can't buy life insurance coverage on some else behave, consequently the contract is illegal and void of premium return.
Other Insurances
....
waiver of insurable interest
Marine insurance act 1906 + life insurance act 1774.
Insurers become insolvent and affairs in hands of a liquidator
Reform of insurable interests (life and related insurance)
....
Clause 2 provides a non exchasutive list of cases in which insurable interest may be proved in life related insurance
Clause 3 regulates return of the premium
Application of insurable interest
life insurance
Family relationships - every person is presumed to have unlimited insurable interest in his or her own life.
- Spouses ONLY - have unlimited insurable interest in each other.
Business relationships:
- Partner - Must be legally obliaged to buy each other out on the death of one of them. Giving them an insurable interest
- Employer and employee - limited to sum of their wage/salary. anything beyond is an expectancy
- Creditor and debtor - They may lose financially if debtor dies before money is repaid
Property insurance
...
Insurance of profit - Business interruption lost following damage to property (founded on a legal right means its insurable)
liability insurance
...
Reinsurance
...
5.4 Explain duty of fair presentation in non consumer insurance
Misrepresentation
"material fact" - 'prudent underwriter' would deem material rather than opinion of a reasonable person.